Home › Gran Canaria › Life Insurance
Independent insurance advice · personal service since 1998
Life Insurance in Gran Canaria
Life insurance can provide a lump sum for the people who depend on you, help clear a mortgage or replace part of the income your household would lose after a death. The right starting point is not the cheapest premium, but three questions: how much your family would need, for how long, and who should receive the benefit. At C1 Broker we review those points before comparing offers from different insurers for residents in Gran Canaria.
- Family protection: cover based on debts and household income
- Beneficiaries: clear wording that can be reviewed over time
- Mortgage: coordinate outstanding debt with family protection
- Local office: Playa del Inglés
Request a life insurance quote
For family protection, a mortgage, or a second opinion on a policy you already have. An initial comparison can be prepared with a small amount of information; supporting documents and the health questionnaire are reviewed later, once you know which options are worth considering.
We compare life insurance from these providers
OUR FULL RANGE OF SERVICES ON GRAN CANARIA
Comprehensive coverage from a single source
How it works
From the form to a useful comparison
Complete the form
Tell us your date of birth, the approximate amount of cover you want, how long you need it for, whether there is a mortgage and whether you smoke. If you are unsure how much cover to choose, we can start with the outstanding debt, household costs and the income you want to replace.
Define the protection you need
Michael Dittkrist will contact you, normally the same day or the next working day. We look at who you want to protect, which financial commitments would remain, whether there is a mortgage, how long support would be needed and how you want the beneficiaries to be arranged.
Compare the options
We compare several proposals and explain the sum assured, term, premium structure, exclusions, optional benefits and beneficiary wording. If you already have a policy, we compare it with the new options before you consider changing or cancelling anything.
Your local contact
Life insurance advice in Gran Canaria
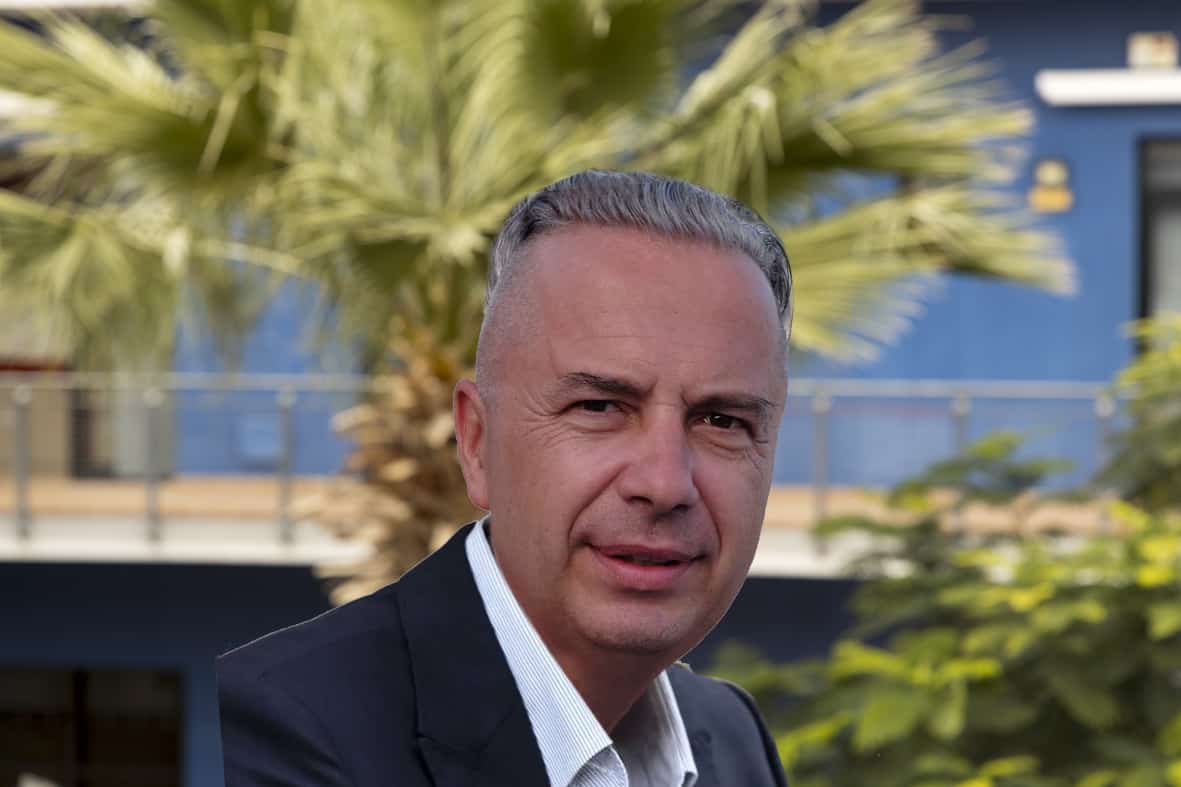
Michael Dittkrist, C1 Broker insurance broker in Gran Canaria
Michael Dittkrist
Michael Dittkrist is an insurance broker with C1 Broker in Gran Canaria and advises clients from the Playa del Inglés office across the island. With life insurance, the discussion usually focuses on five points: how much cover the family genuinely needs, how long the protection should last, how it interacts with a mortgage, who should be named as beneficiary and which additional benefits are worth comparing. If you already have a policy, we also review its current terms before proposing an alternative.
- Phone: +34 928 988 538
- Mobile: +34 634 10 62 16
- Email: [email protected]
- Office: Av. Tirajana 16 Bj, 35100 Playa del Inglés, Gran Canaria
- Languages: English, Spanish and German
Reviews
Reviews of our Playa del Inglés office
★★★★☆
4.2 out of 5 stars from 46 reviews on the Google Business Profile for our Playa del Inglés office. The reviews are collected and published by Google; we do not select or filter them.
C1 Broker Gran Canaria
Data as of September 2026, publicly visible on Google
The beneficiary clause determines who receives the payout
A life insurance policy does not simply pay “the family”. The benefit is paid to the people named as beneficiaries in the contract, and the wording of that clause can be just as important as the amount of cover itself. It should be clear who is to receive the money, in what order and what should happen if one of those people dies before the insured person.
The beneficiary wording should be reviewed when your circumstances change: marriage, a new partner, children, separation, a new mortgage, repayment of a debt or a major change in your assets. A formula that made sense years ago may no longer reflect what you want today. It is also worth avoiding vague wording when your real intention is to protect one person first and others afterwards.
For example, someone living in Maspalomas may want their partner to receive the benefit first and their children to receive it if the partner cannot. Rather than leaving the clause open-ended, we review the order of beneficiaries, the identification needed and whether substitute beneficiaries should be included. The policy and applicable law determine the final legal effect, so particularly complex cases should also be reviewed with the appropriate legal or tax professional.
Mortgage in Gran Canaria: coordinating the bank, the debt and the family
When life insurance is linked to a mortgage, three figures need to be kept separate: the sum assured, the outstanding loan and the amount you want your family to receive. They are not always the same. The policy may also name the bank as beneficiary, creditor or assignee depending on how the arrangement is structured. That is why knowing the remaining mortgage balance is not enough; the wording of the policy also matters.
A financed home in Playa del Inglés
Suppose there is €120,000 left on the mortgage and you want €180,000 of life cover. If the contract provides for the bank to be paid first up to the outstanding balance, the remaining amount could then go to the beneficiaries you have named. The actual result depends on the precise wording of the policy and on any assignment or agreement connected with the loan. Before you take out the policy, we check with you which document determines that priority.
The debt changes over time; the protection may need to change as well
A mortgage normally falls year by year. The amount of family protection you need may develop differently: your children may become financially independent, your savings may increase or other debts may disappear. It is therefore worth reviewing periodically whether the amount and term still match the original need.
For a useful comparison we need to know the remaining loan balance, how many years are left, what other financial commitments exist and who you want to protect in addition to the bank. With that information we can compare cover that tracks the debt, additional family protection or a combination of both.
Tax and residence: review them before finalising beneficiaries
The tax treatment of a life insurance payout depends on the relationship between policyholder, insured person and beneficiary, as well as family relationship and tax residence. In Spain there may be implications for Inheritance and Gift Tax, while the Canary Islands can apply their own reductions or allowances depending on the circumstances. It is therefore unwise to design a policy around a single lump-sum figure without also considering who will actually receive the benefit.
If a beneficiary lives outside Spain, if you own assets in more than one country or if you expect to change residence, the position can become more complex. The same insurance policy may have different tax consequences depending on where the people involved are resident when the payout occurs. International cases should therefore be reviewed individually rather than by applying a single rule.
C1 Broker does not provide tax or legal advice. Our role is to help you compare insurance contracts, sums assured, terms and policy clauses. Where the family or financial structure has special features, we recommend clarifying the tax or succession position with a professional first and then using that information to structure the beneficiaries and cover correctly.
Six points worth comparing before you take out a policy
Two policies with a similar starting premium can behave very differently over time. As well as price, we compare the sum assured, term, premium development, health underwriting, additional benefits and beneficiary wording. The goal is to understand what you are buying, not simply which figure is lowest on day one.
Sum assured
How much your beneficiaries would receive
- We start with debts, household income and the people who depend on you
- The sum assured can be level or tailored to a need that reduces over time
- Too little cover leaves a gap; too much may increase the premium unnecessarily
Term
How long you need the protection
- The term may match a mortgage, a family stage or your working life
- Products set different age limits and renewal rules
- If your circumstances change, check whether the original term still makes sense
Premium
How the cost may change over time
- Some premiums change with age while others follow a different structure
- Do not compare only the first year's cost
- We look at how the premium may develop over the period you actually need
Health
What information the insurer asks for
- Health questions must be answered fully and accurately
- Age, amount of cover, occupation and medical history can affect underwriting
- The insurer may accept, exclude, load the premium or ask for more information
Additional benefits
Disability and critical illness
- Permanent disability or critical illness may be available as optional benefits
- Definitions and exclusions vary between insurers
- Compare the actual benefit, not just the marketing name of the cover
Beneficiaries
Who receives the payout and in what order
- The clause should reflect who you want to protect and in what order
- Substitute beneficiaries may be useful in some circumstances
- With a mortgage, we review how the beneficiary wording interacts with the bank and the debt
The exact scope of each benefit depends on the policy wording and the insurer’s terms. A comparison helps to identify differences, but the final cover is always the cover stated in the accepted and issued contract.
For an initial comparison we normally need your date of birth, approximate sum assured, term, reason for the cover, whether there is a mortgage and whether you smoke. During the formal application the insurer will then specify which medical questions or additional documents are required for underwriting.
If the protection is linked to a property, you may also want to review our home insurance in Gran Canaria. For the rest of the products handled from Playa del Inglés, see our Gran Canaria insurance overview.
The information on this page is general and current as of October 2026. It does not replace an individual policy review or legal, tax or financial advice. The insurance contract, the insurer’s terms and the law applicable to the individual case always take precedence.
When it is worth reviewing a life insurance policy you already have
A policy taken out several years ago may still be valid but no longer fit your current life. The mortgage may be much smaller, your children may no longer depend on you financially, you may have a new partner, changed occupation or built up more savings. Any of those changes can alter the amount and duration of cover that makes sense.
It is also worth checking how the premium has developed, whether you still need every additional benefit and whether something important is now missing. A second opinion should not simply compare two prices: it should put the sum assured, term, exclusions, medical underwriting, beneficiaries and future cost side by side.
We do not recommend cancelling an existing policy until the new insurer has accepted the risk, you know the final terms and the start date is confirmed. A new application involves fresh underwriting and may result in exclusions, premium loadings or different conditions. Keeping the existing contract until the alternative is confirmed avoids an unintended gap in protection.
If you want a second opinion, send us the current policy and the latest renewal notice. We can compare them with new proposals and explain the differences before you decide. For a broader review of your protection, see our Gran Canaria insurance services.
Acceptance, pricing and benefits depend on each insurer and on the information declared in the application. This page explains general comparison criteria and does not constitute a contractual offer.
Frequently asked questions about life insurance in Gran Canaria
How much life insurance should I arrange for my family?
There is no single correct amount. As a starting point we look at the outstanding debts, the income that would disappear from the household, the people who depend on you financially and how long they would need support. You can also separate the amount needed to clear debts from the additional family buffer. We compare several sums assured so you can see how the premium changes before deciding.
Can I change the beneficiaries after taking out the policy?
Many policies allow beneficiaries to be changed, but the policy wording and any special or irrevocable designation must be checked first. Marriage, separation, children, repayment of a mortgage or another major family change are all good reasons to review the clause. Any change should be recorded correctly by the insurer so there is no uncertainty when a claim occurs.
Do I need life insurance if I have a mortgage?
A mortgage is a common reason for arranging life insurance, but it does not by itself determine how much cover you need. We look at the loan, any conditions agreed with the bank and the protection you want to leave for your family in addition to clearing the debt. It is also worth checking whether the mortgage has any discount or pricing condition linked to the insurance and what happens if you change provider.
I already have a policy linked to the bank. Is it worth reviewing?
Yes. Check the current sum assured, term, beneficiary wording, how the premium develops and whether the contract is still tied to any condition of the loan. If the debt has fallen substantially, the original structure may no longer be the most suitable. We do not cancel anything until the existing policy has been compared with the alternatives and any new cover has been accepted.
Do I have to disclose old medical conditions?
You must answer the insurer’s questions fully and accurately. The questionnaire can vary according to age, the amount of cover and the product. Some circumstances may require additional information or medical evidence. If a question is unclear, it is better to ask before answering rather than guess what the insurer is trying to establish.
What happens if I move to another country?
Tell the insurer about the change of address. A move can affect the contract, communication with the insurer and, in international situations, the tax treatment of a future payout. If you already know that a move is likely, mention it during the comparison so that products can be assessed with that in mind and obtain tax advice where necessary.
Should I cancel my current policy before taking out another one?
No. First obtain the new insurer’s acceptance, review the final sum assured, exclusions, premium and start date, and make sure the new cover is actually in force. Only then should the cancellation of the previous policy be coordinated. Cancelling too early can leave you without protection if the new application does not proceed as expected.
C1 Broker Gran Canaria – Playa del Inglés office
A new policy or a second opinion on your current life insurance
No obligation · We normally respond the same day or the next working day