Home › Gran Canaria Insurance › Health Insurance
C1 Broker · Independent insurance broker since 1998
Private Health Insurance
in Gran Canaria
For British residents and international families living between Maspalomas and Las Palmas. The island’s main public acute hospitals are in Las Palmas, while private access in the south depends on the medical network of the policy you choose. We check that network with you before you sign.
- Advice in English: from first conversation to claim support
- Medical network: which hospitals and doctors are actually included
- Island hospitals: private options in both north and south
- Local office: Playa del Inglés
Request a health insurance quote
About 3 minutes to complete, with a reply usually the same or next working day
Health insurers we work with include
Our insurance options in Gran Canaria, with other lines available on request
Four core areas, one local contact
How it works
From the form to a proper comparison
Complete the form
Tell us who needs cover, when you want it to start and what matters most to you. It takes only a few minutes and can be completed in English.
Clarify the important details
Michael Dittkrist will get back to you, usually the same or next working day. On this island, one question matters immediately: where do you live, and which hospital would you want to use if you needed treatment?
Compare plans side by side
We explain several options in English, including benefits, copayments, waiting periods, exclusions and the hospitals included in each medical network.
Your local contact
Health insurance advice in Gran Canaria
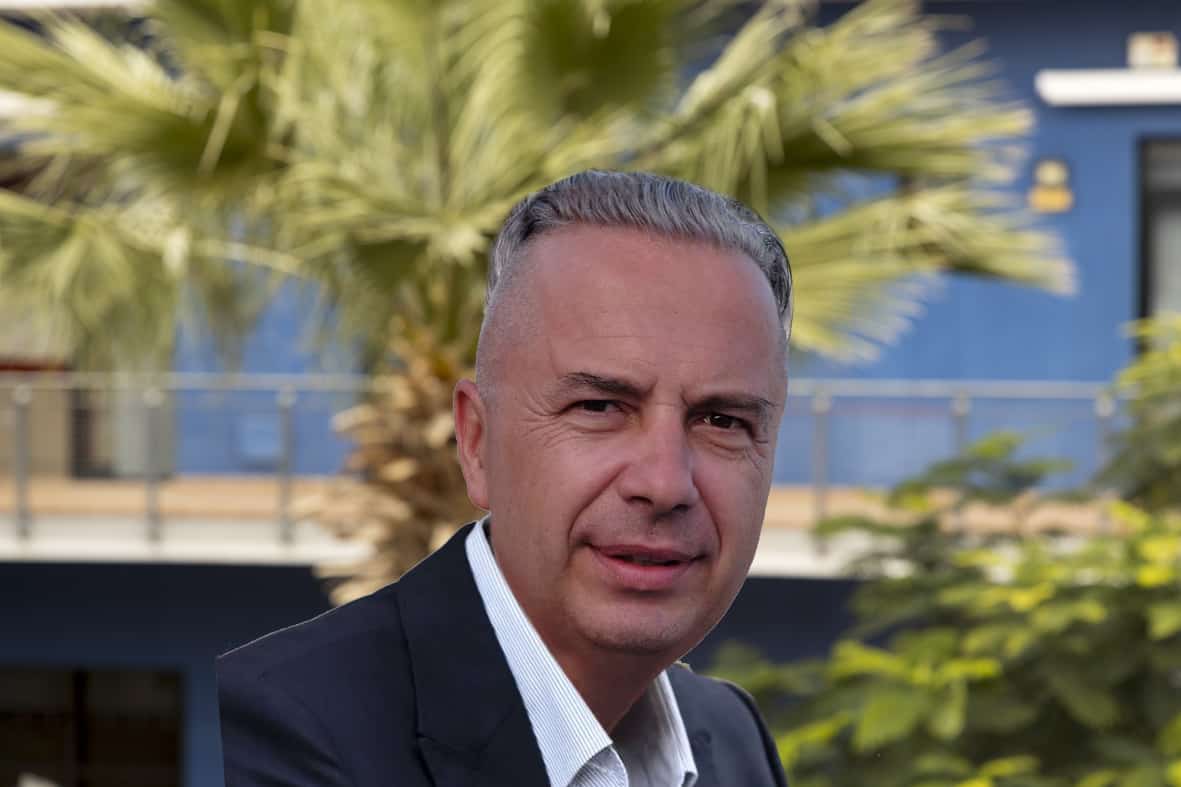
Michael Dittkrist
Insurance broker for C1 Broker in Gran Canaria. Michael advises clients across the island, from Maspalomas, Vecindario and Mogán to Las Palmas and the north. For health insurance, that means checking which hospitals and specialists are included in the plan and explaining copayments, waiting periods and policy conditions in English before you apply.
- Telephone: +34 928 988 538
- Mobile: +34 634 10 62 16
- Email: [email protected]
- Office: Av. Tirajana 16 Bj, 35100 Playa del Inglés, Gran Canaria
- Languages: English, German and Spanish
Reviews
Reviews for our Playa del Inglés office
★★★★☆
4.2 out of 5 stars from 46 reviews on the Google Business Profile for our Playa del Inglés office. Reviews are collected and published by Google; we do not select or filter them.
C1 Broker Gran Canaria
Figures as of September 2026, publicly viewable on Google
Public or private: where you may need to travel for treatment in Gran Canaria
The island’s two main public acute hospital complexes are in Las Palmas: Complejo Hospitalario Universitario Insular-Materno Infantil and Hospital Universitario de Gran Canaria Doctor Negrín. For residents in the south and east of the island, specialist and hospital care can therefore involve travelling to the capital. From Playa del Inglés, that is roughly 50 kilometres along the GC-1.
The private map is different. There are private hospitals and emergency services in the south as well as in Las Palmas, but being privately insured does not automatically give access to every one of them. What matters is the medical network – the cuadro médico – attached to the exact plan you choose. That is why we check the network before the application is submitted.
Private hospitals in Gran Canaria
These are among the main private hospitals used for inpatient treatment on the island, with facilities in both the north and south. They are not partners of C1 Broker; whether they are available to you depends on the insurer and the medical network of your specific plan.
North, Las Palmas
Hospitales Universitarios San Roque
- C/ Dolores de la Rocha 5 35001 Las Palmas de Gran Canaria
- 928 40 40 40
- hospitalessanroque.com
North, Las Palmas
Hospital Universitario Vithas Las Palmas
- C/ León y Castillo 292 35005 Las Palmas de Gran Canaria
- +34 928 297 151
- vithas.es
South, Meloneras
Hospitales San Roque Maspalomas
- C/ Mar de Siberia 1 35100 Meloneras, San Bartolomé de Tirajana
- 928 40 40 40
- hospitalessanroque.com
South, San Agustín
Hospiten Clínica Roca
- C/ Buganvilla 1 35100 San Bartolomé de Tirajana
- +34 928 76 90 04
- hospiten.com
Three situations, three different insurance needs
What counts as a good health insurance plan depends on your circumstances more than on the product name. These three examples show why people living on the same island can need very different solutions.
Retired British couple in Mogán
If you are entitled to Spanish public healthcare through a registered S1 or another recognised route, private insurance is not a replacement requirement but a personal choice. For many retirees in the south, the attraction is shorter travel and easier access to private specialists or hospitals closer to home. If private access would add little to your circumstances, we will say so.
Family with two children in Vecindario
Here, frequency of use matters. A policy with a copayment for each visit usually has a lower monthly premium and can make sense when healthcare use is light. With young children, regular appointments can quickly change that calculation. Waiting periods for planned treatment, maternity or other benefits also need to be checked before choosing the plan.
Self-employed professional in Las Palmas
Someone registered as autónomo and paying into the Spanish Social Security system is normally covered by the public system. Private insurance is therefore usually an additional choice, often for faster access to specialists or a wider private network. If work involves regular travel to mainland Spain, the geographical scope of the policy also matters.
What does private health insurance cost in Gran Canaria?
There is no single price that applies to everyone, so we deliberately do not publish a headline figure. Premiums depend on age at entry, who is insured, whether you accept copayments and how broad the medical network is. On Gran Canaria, that last point can make a noticeable difference because a plan limited mainly to Las Palmas may be priced differently from one that also gives access to private hospitals in the south.
If you tell us the ages of the people to be insured, where you live and who needs cover, we can compare actual monthly premiums from several insurers rather than giving you a broad range that may not apply to you.
Healthcare evidence for British residents in Spain
British nationals are no longer EU citizens for Spanish residence purposes, so the healthcare evidence required depends on the residence or visa route being used. Some applicants need comprehensive private medical insurance, while people who are already entitled to Spanish public healthcare through employment, self-employment, an eligible S1 or another recognised route may be in a different position. A short-term travel policy is generally not designed to replace comprehensive resident health cover where that is required. The competent immigration authority decides what evidence is accepted in each case.
If you already have recognised access to the Spanish public system, private insurance may still be useful for convenience, network choice or faster private appointments, but it is a separate decision from your public entitlement. If insurance evidence is needed for a residence application, we can provide the insurer documentation for the policy you arrange; you should confirm the exact immigration-document requirements with the authority handling your application.
The information on residence and healthcare on this page is general information as at September 2026. It does not replace individual immigration, legal or healthcare advice. Your residence route, entitlement to public healthcare and the terms of the insurer’s contract are decisive.
Frequently asked questions about health insurance in Gran Canaria
I have pre-existing medical conditions. Can I still get a policy?
Often yes, but not necessarily with every insurer or on standard terms. Health applications normally include medical questions that must be answered accurately. Depending on the condition, an insurer may apply an additional premium, exclude a condition or decline the application. Age limits also vary. We can check likely options before you commit to a formal application.
Are prescription medicines covered?
Usually not as part of the basic medical cover. Spanish private health policies generally focus on consultations, diagnostics and hospital treatment, while pharmacy costs are separate. Some insurers offer an optional pharmacy benefit that reimburses part of the cost of prescribed medicines up to an annual limit. If you use regular medication, tell us before we compare plans.
Does my Spanish health policy cover me when I visit the UK?
That depends on the plan. Many Spanish policies are designed mainly for treatment in Spain, while international treatment requires a plan or extension that expressly provides overseas cover. Emergency travel assistance may also be subject to separate limits. Tell us how often and how long you spend in the UK so we can focus on policies whose territorial cover matches that pattern.
How do I check whether my doctor is in the medical network?
Each insurer publishes a medical directory – the cuadro médico – organised by province, town and specialty. For Gran Canaria, search under the province of Las Palmas. Two plans at a similar price can provide access to different hospitals or specialists, so we check the directory with you before you apply. Networks can change over time, so the insurer’s current directory is the reference point.
What does copago mean in a Spanish health insurance plan?
A copago is a fixed amount you pay when you use certain medical services, in addition to the monthly premium. Plans with copayments usually have a lower premium and can work well when healthcare use is light. If you expect frequent paediatric, specialist or diagnostic visits, a plan without copayments may be easier to budget for. We compare the two approaches using your likely pattern of use.
Are there waiting periods before I can use certain benefits?
Usually yes, and the waiting period is not the same for every benefit. Emergency treatment and straightforward consultations may be available immediately, while planned procedures, hospital admissions, maternity or other benefits can have a qualifying period. The length and scope vary significantly between insurers, so we point out the relevant clauses before you choose.
Do doctors in Gran Canaria speak English?
Some do, particularly in areas with a large international population, but it cannot be guaranteed for every hospital, specialty or doctor. We can check the insurer’s medical directory for clinics near you and any languages they list. Your policy advice and our support are provided in English regardless of the language used by the treating doctor.
What happens to my policy if I move to another island or to mainland Spain?
Spanish health policies are generally designed for use across Spain, so moving does not automatically mean the contract ends. What can change is the local medical network available to you. A plan that works well in Gran Canaria may give you different hospitals after a move to Tenerife, another island or mainland Spain. Tell us before you move and we can review whether the existing insurer still fits.
I already have Spanish health insurance. What do you need to compare it?
Send us the current policy schedule and wording, the date of birth of everyone to be insured, your place of residence and the current renewal date. If you later decide to switch, the insurer may also need identification details and a Spanish bank account for direct debit. We coordinate the start date of the new policy so that you do not create an unintended gap in cover.
A new policy or a second opinion on your existing cover
No obligation · We usually reply the same or next working day
Prefer to speak to us? +34 928 988 538 or +34 634 10 62 16