Home › Lanzarote Insurance › Car Insurance
Independent · Local · Insurance in Spain since 1998
Car Insurance
in Lanzarote
For residents and second home owners on the island: compulsory third party cover, extended cover or fully comprehensive, arranged around the way the car is actually used, whether it runs every day, stands at a holiday home for months, or arrived with foreign plates.
- Advice in English
- Independent broker
- Claims handled for you
- A real office in Tías
Request your quote
About five minutes to complete, an answer within 24 hours
We compare the leading insurers in Spain for you
Everything we cover on Lanzarote
One broker for the policies you actually need
Three steps to the right policy
Send your enquiry
You fill in the form in English, in about five minutes. Tell us how the car is used, because that is what decides which level of cover is worth paying for.
A personal conversation
William gets back to you within 24 hours, by phone, email or video call, whichever suits you. If you prefer, come into the office in Tías.
A comparison, not a sales pitch
You receive a written comparison of the policies that fit your car, with the excess and the exclusions spelled out. No obligation, and no pressure to decide on the call.
William Smith
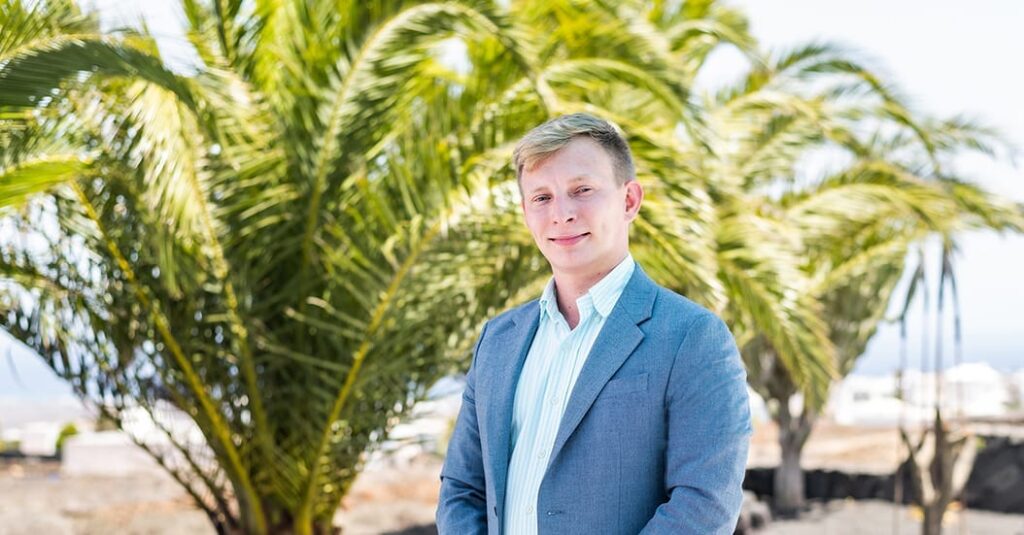
C1 Broker's representative on the island, based in Tías
“I started out at AXA in Manchester underwriting fleet business, then spent years in compliance for an international telecoms company. That background is why I read the small print before I recommend anything: and why I would rather tell you a policy is wrong for you than sell it.”
- Phone: +34 928 132 334
- Mobile: +34 611 604 174
- Email: [email protected]
- Office: Calle Libertad 24, 35572 Tías, Lanzarote
- Languages: English and Spanish
4.8 out of 5 from 169 Google reviews
Excellent service from Will — quick, easy and efficient from start to finish. Everything was handled smoothly and professionally. Highly recommended
Chris Anderson
Lanzarote · 2026
We have 3 policies with C1, two for car insurance (which was more competitive on both counts than our previous provider.) and house insurance. All policies in English. Great service from Will at C1
Karen MS
Lanzarote · 2023
What does car insurance cost on Lanzarote?
Two things decide most of your premium: how much cover you buy, and what your claims record looks like on paper. The vehicle, your age and the address where the car is kept all play their part, but on an island this size the difference between one municipality and the next is small next to those two.
The ranges below are for orientation. The figures come from our Mallorca car page rather than from a Lanzarote sample, and they are not binding quotes: your own number comes out of your details and out of a comparison across several insurers. If you are bringing a claims history over from another country, ask your previous insurer for a written statement before you cancel the policy. It is considerably harder to obtain once the policy has lapsed, and without it a discount you have earned is difficult to prove.
Runabout kept at a holiday home, driver aged 55
Extended third party with theft, fire and glass · example range around €250 to €400 a year
Recently re-registered SUV, driver aged 40
Fully comprehensive with an excess · example range around €500 to €900 a year
Three ways a car gets used here, and what each one needs
At the start of 2025 the DGT counted 147,159 registered vehicles on Lanzarote. The island’s resident population is 166,878 (INE, 2025). In our experience a noticeable part of that fleet belongs to people who are not here all year, and that produces three quite different situations. A policy is priced and worded for one of them, so it is worth being clear which one you are in before you compare premiums.
Everyday car
Driven all year on the island
- Short, repetitive journeys, and a car that is rarely more than half an hour from home. The cover you are most likely to call on is assistance, not a total loss.
- On an older car that argues for putting the money into assistance, glass and a replacement vehicle rather than into fully comprehensive.
- Ask how many days a replacement vehicle is provided for. On an island, a part that has to be shipped in can keep your car off the road longer than the policy allows.
Second car
Kept at the holiday home
- A car that stands for months is still exposed to theft, fire, storm and flooding, so cutting back to third party alone is rarely the saving it looks like.
- What no policy covers is what standing still does to a car: a flat battery, seized brakes, perished tyres. That is maintenance, not a claim.
- Say how long the car normally stands and who drives it while you are away. A named second driver costs little to add and settles the question in advance.
Imported vehicle
Brought over with foreign plates
- Taking up residence here normally means re-registering the vehicle on Spanish plates. The point to get right is that there is no day on which the car is driven without valid cover.
- Until the Spanish plates are issued, a Spanish policy is usually not yet available to you. We check what your existing policy still covers in the meantime.
- Your foreign licence and your no claims record are two separate questions, and insurers treat them differently. We put both to the insurer before you commit.
Short journeys are the reason to check where your assistance starts
This is the clause we look at first on Lanzarote, and it is the one almost nobody reads. Roadside assistance is not automatically provided from your own front door. Some Spanish policies only send help once the vehicle is a set distance away from the address on the policy, and the thresholds in the market run from a few hundred metres to around 30 kilometres. Others provide assistance from kilometre zero, which includes a car that will not start on your own driveway.
On a long daily commute that distinction barely matters, because you break down out on the road anyway. Here it matters a great deal. Journeys on the island are short and most of them stay well inside a radius that a restrictive wording would exclude, so a policy that only helps beyond that radius is, for the way people drive here, close to useless. In our experience the call that comes in is far more often a car that will not start at home than one stranded on the LZ-2.
Two related points are worth settling at the same time. First, how far the vehicle can be towed and whether you can choose the garage, because parts and specialist workshops on an island are not always where you need them. Second, whether the assistance covers the people in the car as well as the car itself, which some wordings treat as separate cover with its own thresholds. We go through all three with you in English before you sign.
Storm and flood damage to the car, and what the Consorcio does
Rain here arrives rarely and all at once. On 12 April 2025 heavy rain flooded parts of Arrecife and Teguise, with more than 200 incidents reported, among them flooded garages and underground car parks. That is the situation in which people discover what their motor policy does and does not do.
For events on that scale Spain has a separate mechanism, the Consorcio de Compensación de Seguros. For vehicles the rule is more generous than most drivers assume, and it is worth knowing precisely. Since 1 July 2016, when the eighth final provision of Ley 20/2015 took effect, the Consorcio covers material damage from extraordinary risks to every vehicle with Spanish plates insured under a Spanish motor policy, without exception. Before that date, cars insured on third party cover alone were outside the scheme.
So flooding, atypical cyclonic storms, earthquake and volcanic eruption are handled through that route rather than through your ordinary cover, and they are handled even if your policy is third party only. What your own policy level still decides is everything ordinary: hail on the bodywork, a tree branch in a gale, a break-in. Those are your insurer’s business, and only if you bought cover for them.
Third party, extended, or fully comprehensive
Third party (seguro a terceros) is the compulsory part and covers damage you cause to others, never your own car. Extended third party (terceros ampliado) adds theft, fire and glass. Fully comprehensive (todo riesgo) also pays for damage to your own vehicle, with or without an excess. The three levels work the same way across Spain, and we describe them in more detail on our car insurance in Spain page.
Which one is right depends on what the car is worth and on what losing it would mean for you, not on a rule of thumb. We will not talk you into the top level on a car whose market value no longer justifies it, and if you want to run a nearly new vehicle on third party alone, we will tell you plainly what you are giving up before you decide.
ITV dates, renewals and the paperwork we keep track of
An ordinary passenger car in Spain has its first ITV, the technical inspection, four years after first registration. From then until it is ten years old the inspection is due every two years, and after ten years it becomes annual. Those dates run from the vehicle rather than from your policy, and they are easy to lose track of when the car is only used for part of the year.
We put the ITV date in your file alongside the renewal date and flag it to you before either falls due. The same goes for the renewal itself: Spanish motor policies normally roll over unless notice is given in time, so if you want to change insurer, the date matters more than the offer. We would rather raise it with you a few weeks early than explain afterwards why the switch has to wait a year.
Driving across the seven municipalities
Our clients drive right across the island, and where the car is kept shapes the sensible policy more than where it is driven. In Arrecife, which carries by far the largest share of the island’s vehicles, the everyday questions are street parking, minor knocks and glass. In Tías, Puerto del Carmen, Costa Teguise and Playa Blanca, where hire cars and visitors are part of everyday traffic, it is worth being sure of your legal cover and of how an accident with a foreign driver gets settled.
In Teguise, San Bartolomé, Tinajo, Yaiza and Haría the pattern is different again: longer runs between villages and vehicles parked outside rather than in a garage. The smaller places follow the same logic, from Tahíche, Guatiza, Arrieta, Punta Mujeres and Órzola in the north to La Santa and La Vegueta on the west side and Femés, El Golfo and Playa Quemada in the south.
Wherever you are on the island, an accident is reported to us at the office in Calle Libertad 24 in Tías, in English, and we take it from there. If the other vehicle is a hire car or is registered abroad, that is exactly the kind of file where having a broker on the island rather than a call centre abroad changes how quickly it gets settled.
Frequently asked questions
Is car insurance compulsory in Spain?
Third party liability cover is compulsory for every vehicle registered in Spain, and that applies on Lanzarote exactly as it does on the mainland. Everything above it, glass, theft, fire, damage to your own car, a courtesy car, legal costs, is your choice. The compulsory part is also the cheapest part of the policy, so the real decision is what you add to it.
Do my no claims years from the UK or Germany count in Spain?
Often yes, if you can evidence them. Many Spanish insurers will take a claims history from another European insurer into account, and a written statement from your previous insurer is usually what they ask for. It is worth requesting that letter before you cancel the old policy, because it is harder to obtain afterwards. We ask the insurers on your shortlist how they treat it before you decide.
I hardly drive on the island. Is third party cover enough?
It depends on what the car is worth and what you would do if it were written off, not on how many kilometres you cover. Low mileage does argue against paying for fully comprehensive on an older car. It does not remove the risk of theft, of hail or storm damage while the car is parked, or of a claim against you. What we usually check first on a low mileage policy is where the roadside assistance begins, because that is the cover you are most likely to use.
Where does roadside assistance start, and why does it matter here?
Not every policy assists you from your own front door. Some wordings only send help once you are a set distance from the address on the policy, and the thresholds in the Spanish market vary from a few hundred metres to around 30 kilometres. On an island where most journeys are short and close to home, a policy that only helps beyond a radius is close to useless. We check that clause in the wording before we recommend a policy.
My car stands at the holiday home for months. What should I watch?
The policy continues to run while the car is parked, and theft, fire and storm damage are exactly the events a stationary car is still exposed to. What no policy pays for is wear that comes from standing: a flat battery, seized brakes, perished tyres. Tell us how long the car normally stands and we will look at whether the cover you are paying for still matches the way you use it.
When does my car have to pass its ITV?
For an ordinary passenger car in Spain the first ITV is due four years after first registration. From then until the car is ten years old it is every two years, and after ten years it is annual. The dates run from the vehicle, not from your policy, but we keep the ITV date in your file alongside your renewal date and flag both to you in good time.
What happens after an accident if my Spanish is limited?
You call us. We take the details in English, deal with the insurer, the garage and, where necessary, the other driver’s insurer in Spanish, and keep you informed in English until the claim is settled. If the other car is a hire car or is registered abroad, that is precisely the kind of file we would rather handle for you than hand back.
C1 Broker Lanzarote · Visit us in Tías
Your car on Lanzarote, insured for the way you actually drive it
Free advice · an answer within 24 hours · no obligation