Home › Lanzarote Insurance › Business Insurance
Independent · Local · Insurance in Spain since 1998
Business Insurance
in Lanzarote
For people running a business on the island, from a single bar to a block of holiday apartments: liability, premises and contents, the staff cover your convenio obliges you to hold, and the cover that keeps paying the fixed costs while your doors are shut for repairs.
- Advice in English
- Claims handled for you
- Independent broker
- A real office in Tías
Request your quote
About five minutes to complete, an answer within 24 hours
We compare the leading commercial insurers in Spain for you
Everything we cover on Lanzarote
One broker for the policies you actually need
Three steps to the right policy
Tell us what the business does
The form takes about five minutes and is in English. The activity written on your licence is the part that matters most, because it decides which limits an insurer is willing to offer you at all.
We go through the risks with you
William works through the premises, the equipment, the people and the policies you already hold. Most of that conversation is about what would stop you trading, not about which product to buy.
You get the comparison in writing
Several insurers side by side, with the limits, the excess and the indemnity period set out in English. Nothing is signed on the call, and you keep the document whether you buy or not.
William Smith
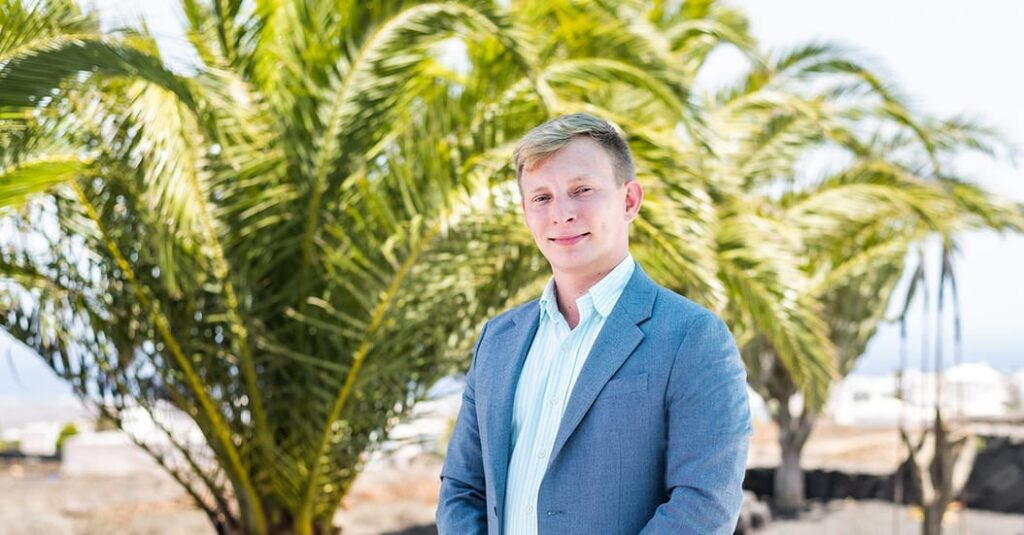
C1 Broker's representative on the island, based in Tías
“I started out at AXA in Manchester underwriting fleet business, then spent years in compliance for an international telecoms company. That background is why I read the small print before I recommend anything: and why I would rather tell you a policy is wrong for you than sell it.”
- Phone: +34 928 132 334
- Mobile: +34 611 604 174
- Email: [email protected]
- Office: Calle Libertad 24, 35572 Tías, Lanzarote
- Languages: English and Spanish
4.8 out of 5 from 169 Google reviews
Excellent service from Will — quick, easy and efficient from start to finish. Everything was handled smoothly and professionally. Highly recommended
Chris Anderson
Lanzarote · 2026
We have 3 policies with C1, two for car insurance (which was more competitive on both counts than our previous provider.) and house insurance. All policies in English. Great service from Will at C1
Karen MS
Lanzarote · 2023
What decides the price of business cover here
We do not publish a price for business insurance, because a fixed figure would be misleading. What we can show you is how far apart two quotes on this island sit, and what puts them there.
A self employed therapist renting a treatment room in Arrecife needs a modest liability limit, holds almost no stock and employs nobody. That policy is small and is arranged in a couple of days. A family running eight holiday apartments in Costa Teguise insures a building, its contents, the liability towards guests and the income lost if a floor has to be closed, and every one of those figures has to be set individually. The second policy is not the first one multiplied. It is a different policy.
What sits behind the gap, more than anything else, is the activity written on your licence. On an island where so much commercial activity runs through tourism, the same square metres can be a shop, a bar with a kitchen or a dive centre taking clients into the water, and an insurer prices those three nothing alike. Before you spend anything, we can tell you which part of your quote the licence is driving and which part you can still influence.
Three businesses, three things that go missing first
These are the gaps worth looking for when you read a policy that somebody else arranged. In each case the cover existed. It simply stopped short of what the business needed on the day.
Bar or restaurant
The kitchen is out of action
- Fire, smoke and the extinguishing damage to the kitchen itself are what a commercial multi risk policy is built for, and that part usually pays without argument.
- The rent, the payroll and the supplier contracts carry on running while nothing is being served. Without a loss of income section, none of that is covered.
- Worth reading in your own wording: whether the extraction system and the terrace are named as insured, because a good many kitchen fires start in one and spread to the other.
Holiday apartments
A leak takes two units off the market
- Water damage to your own walls, floors and furniture sits inside the building and contents cover, and so does the damage you cause to the neighbour below.
- The bookings you have to cancel are a separate matter. If the policy was written as a household policy rather than a commercial one, the income was never insured in the first place.
- Check in your own wording: whether the insurer was told the apartments are let to guests. An undeclared commercial use is the argument an insurer reaches for first.
Workshop or dive centre
The equipment is gone
- Theft, fire and storm damage to machinery and equipment kept at the insured address are standard cover, up to the sum you declared for contents.
- Gear that leaves the premises often falls outside it. Compressors on a van, tanks on a boat and tools on a client's site need to be named if they are to be covered.
- One line to look up: the sum insured for contents. Equipment is replaced at today's prices, and a declaration made years ago rarely reaches that far.
The number in your policy that decides whether you reopen
Spanish commercial policies call the loss of income section pérdida de beneficios, and it is where the difference between a business that survives a fire and one that does not usually sits. The wording is more specific than people expect. Cover applies up to the sum insured and for the indemnity period contracted, and it runs for as long as the works needed to repair the damage take. Two things follow from that sentence, and both are worth ten minutes of your time.
The first is that the period is agreed when the policy is issued. Nothing about it adjusts afterwards to suit the size of the loss. Whatever was written into your policy is what you have. The second is that the clock is tied to the repair itself, so what counts is how long that work realistically takes here. Before you sign, put the period next to an honest answer to one question: how long would it actually take to have that kitchen, that roof or that machine back in service here? If the honest answer is longer than the period in the policy, the payments stop while the costs are still running.
There is a further decision, and it is what the section actually pays for. In the wordings we work with, the section is written one of two ways: the standing overheads, meaning rent, salaries, leasing and the bills that do not stop, and the loss of gross profit, which covers the overheads and the margin you would have earned. A business that could survive a few weeks on savings but not the loss of a season needs the second one. We tell you which of the two you are being quoted, because the two are rarely priced the same and are almost never explained at the point of sale.
What the Las Palmas convenio obliges you to insure for your staff
If you employ people in hospitality on Lanzarote, one insurance decision has already been made for you. Lanzarote sits in the province of Las Palmas, and the provincial collective agreement for the hospitality sector applies to every working relationship carried out in the province, including those in companies registered somewhere else entirely. Article 19 of that agreement requires the employer to hold a life policy with an insured capital of €12,020.24. The same amount is payable if an employee is declared permanently and totally unfit for their usual occupation, permanently unfit for any work, or severely disabled, whether the cause is illness or an accident.
There is a qualifying period of one year of service for the disability benefit, and it comes with an exception worth knowing: accidents, whether at work or outside it, are excluded from that waiting time, as are unforeseeable and demonstrable events such as a heart attack. The agreement ran to the end of 2025 and, by its own terms, stays in force until a new one takes its place, so it is the version your business is working under while the successor is being negotiated.
It is also the cover that is easiest to overlook, because nothing in the day to day reminds you of it until an inspection or a claim does. It is inexpensive and quick to put in place. What it is not is optional, and it is not the same thing as the accident cover an insurer may already have bundled into your commercial policy. We check which of the two you actually hold.
Liability, premises and contents: what usually sits in one policy
Most businesses on the island end up with a commercial multi risk policy, and the value of it is that several covers sit under one renewal date and one point of contact. Inside it there is normally public liability, for injury or damage you cause to third parties, and the building and contents cover for the premises, the fittings, the stock and the equipment. Around that, depending on what you do, sit the sections that are easy to forget: goods in transit or off the premises, legal expenses, glass, refrigerated stock, and cyber cover if you take bookings or card payments.
Liability deserves a sentence of its own, because the limit is where policies quietly differ. Your licence, your landlord or the community of owners may each require a minimum, and those requirements do not always agree with each other. When we quote, we ask what you are contractually obliged to hold before we ask what you would like to hold, because a policy that fails the licence condition is a problem waiting for an inspection. Our national page on insurance for companies in Spain sets out the individual covers in more detail if you want to read further.
Letting holiday apartments is trading, and it is insured as trading
Owners letting one or more units to holiday guests are a case we arrange regularly on Lanzarote. It is worth being clear about what that changes. Once you let to guests you are carrying on an economic activity, and the people in the property are no longer family and friends but customers. Both facts belong in the policy. A guest who slips on a wet terrace, a barbecue that scorches the neighbour’s awning and a stay cancelled because a unit is uninhabitable are all business events, and a household policy was not written with any of them in mind.
The question we start with is not a legal one, it is factual: how many units, how much of the year are they let, do you clean and hand over the keys yourself or does an agency do it, and is there a pool. Those four answers move the liability limit and decide whether the loss of income section is worth having. If you also own the property you live in on the island, the home insurance page covers the private side, and the two policies are best arranged so they do not overlap.
Businesses across the seven municipalities
Our office is in Tías, a few minutes from Puerto del Carmen, and that is where most appointments happen. It is not where the work stops. We arrange cover for businesses in Arrecife, where the offices, the trades and the port related firms are concentrated, in Teguise and Costa Teguise, in Yaiza and Playa Blanca, and in San Bartolomé, Tinajo and Haría.
Where you are matters to a business policy in ways that are easy to overlook. A ground floor unit near the seafront is exposed differently from a first floor office inland. A building in a pedestrianised street is harder for a fire engine to reach. A property on a plot with its own well or its own generator has features an insurer wants named. If you would rather we came to you than the other way round, say so when you send the form.
Frequently asked questions
We close for a few weeks each year. Does that change the policy?
It can, and it is a question to settle before you sign rather than after a claim. Leaving premises unoccupied for a longer stretch is the kind of circumstance a wording may treat separately, so tell us how long you close and whether anyone looks in while you are shut. We then ask the insurer to confirm in writing what applies during that period, so that nothing rests on an assumption.
What is the seguro de convenio and does it apply to my business?
It is a life and permanent disability policy that a collective agreement obliges an employer to hold for its staff. For hospitality businesses on Lanzarote the agreement is the provincial one for Las Palmas, and its article 19 sets the insured capital at €12,020.24, payable on death and on permanent total, absolute or major disability. It applies to the working relationship, so it reaches your staff even if your company is registered somewhere else.
How long does business interruption cover keep paying?
For as long as the indemnity period written into your policy allows, and no longer. Spanish wordings tie that period to the time the repair works actually take, and the figure is agreed when the policy is issued rather than set by law. That is the number to check before you sign, because if the period runs out while you are still waiting to reopen, the payments stop and the costs do not.
I let holiday apartments. Is that a home policy or a business policy?
Letting to holiday guests is a commercial use of the property, and a normal household policy is written for something else. If a guest is injured or a leak in your apartment damages the flat below, an insurer that was never told about the letting has a reason to argue. Tell us how many units you let and for how much of the year, and we will look at whether one policy can carry both the building and the liability.
We rent our premises. Who insures what, us or the landlord?
As a rule of thumb the landlord insures the building and you insure what you brought into it: the fit out, the equipment, the stock and your liability towards customers. The line between the two is drawn in your lease rather than by custom, and no two leases put it in quite the same place. Send us the lease with your enquiry and we will tell you which side each item falls on, before you pay for cover somebody else already holds.
We are a one person autónomo business. Is that too small?
No. A self employed tradesman, a therapist renting a treatment room and a consultant working from home all carry a liability that does not shrink with the size of the business. The policies are smaller and quicker to arrange, and the questions we ask are the same ones.
Does the convenio cover apply to our cleaning and maintenance staff as well?
That depends on which collective agreement your company falls under, and the answer follows the activity the business is registered for rather than the job title of the individual employee. An apartment business and a cleaning contractor can sit under different agreements even where the work looks identical from the outside. Your gestor will tell you which agreement applies to you, and once that is settled we arrange the cover it requires.
C1 Broker Lanzarote · Visit us in Tías
Let us look at your business cover
Send us what you do and what you already hold. You get a written comparison in English, and an honest answer about the gaps, whether or not you move your policies to us.